Strap in and get ready to dive deep into the world of auto insurance in Massachusetts. Whether you’re cruising through the scenic roads of Cape Cod or navigating the bustling streets of Boston, understanding the ins and outs of your auto insurance policy is crucial. But how much is auto insurance in Massachusetts, and what factors influence its cost? We’re here to break it all down for you, Backlinko style!
From minimum coverage requirements to the hidden secrets of saving on your premiums, this guide will equip you with everything you need to know. So, put on your seatbelt, and let’s hit the road to uncover the true costs of auto insurance in Massachusetts!
Understanding Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the most stringent auto insurance requirements in the country? What you pay can depend on a variety of factors, but it’s crucial to understand what you’re actually paying for.
Auto insurance in Massachusetts breaks down into several key components. Each of these plays a role in how much you pay and the protection you receive. Let’s dive into what makes up your auto insurance coverage in the Bay State.
Minimum Insurance Requirements for Massachusetts Drivers
Massachusetts requires drivers to have a specific set of insurance coverages. At a minimum, you’re looking at $20,000 per person and $40,000 per accident for bodily injury liability. Property damage liability must be at least $5,000. Uninsured motorist coverage is also a must, matching the bodily injury limits.
But that’s not all. You also need Personal Injury Protection (PIP) insurance, with a minimum of $8,000. This covers medical expenses and lost wages regardless of who’s at fault. This comprehensive approach ensures that Massachusetts drivers are protected in multiple scenarios.
Coverage Options Beyond Minimum Requirements
Here’s the deal: while meeting the minimum is mandatory, it’s often not enough. Opting for additional coverage can save you big bucks in the long run. Consider collision and comprehensive coverage for repairs and non-accident-related damages, like theft or natural disasters. It’s no surprise that many choose to go beyond the basics.
Pro Tip: Increasing your liability limits can provide peace of mind and protect your assets in case of a major at-fault accident.
Other options include gap insurance (if you owe more on your car than it’s worth) and towing and labor coverage. Each of these can be tailored to fit your specific needs and budget, offering greater protection and financial security.
Factors Affecting Auto Insurance Rates

Ever wondered why your auto insurance bill might be higher than your neighbor’s? It’s not just a random number.
The cost of your car insurance in Massachusetts isn’t solely based on your driving habits. Multiple factors come into play, and each one can significantly affect your premium.
Key Factors Impacting Insurance Costs
Let’s dive into the primary factors that influence your insurance rates in Massachusetts. From your age to your car’s make and model, these determinants can make a huge difference in what you pay.
| Factor | Description | Impact Level |
|---|---|---|
| Age | Younger drivers often face higher rates due to perceived inexperience. | High |
| Driving History | Past accidents and traffic violations can increase premiums. | High |
| Vehicle Type | The make and model of your car can affect repair costs and safety ratings. | Medium |
| Credit Score | Some insurers use credit-based insurance scores to assess risk. | Medium |
| Location | Urban areas typically lead to higher rates due to traffic density. | Low to Medium |
Comparing the Impact of Different Factors
Here’s the deal: Age and driving history are two of the most influential factors. Younger drivers and those with a spotty record can expect premiums to soar.
BUT it’s not all doom and gloom. Choosing a vehicle with high safety ratings or improving your credit score can help you snag a better rate.
Pro Tip: Regularly review your policy and shop around. Sometimes, switching providers can lead to significant savings.
Average Costs of Auto Insurance
Would you believe that Massachusetts drivers pay an average of $1,460 annually on auto insurance? That’s a significant chunk of change compared to other states. But here’s the deal: prices can vary dramatically based on where you live and what you drive.
Let’s dive into some specifics. The average cost gives us a starting point, but it’s crucial to understand that your rate isn’t set in stone. Factors like your city, driving record, and vehicle type can cause your premiums to skyrocket.
Variations by City or Region
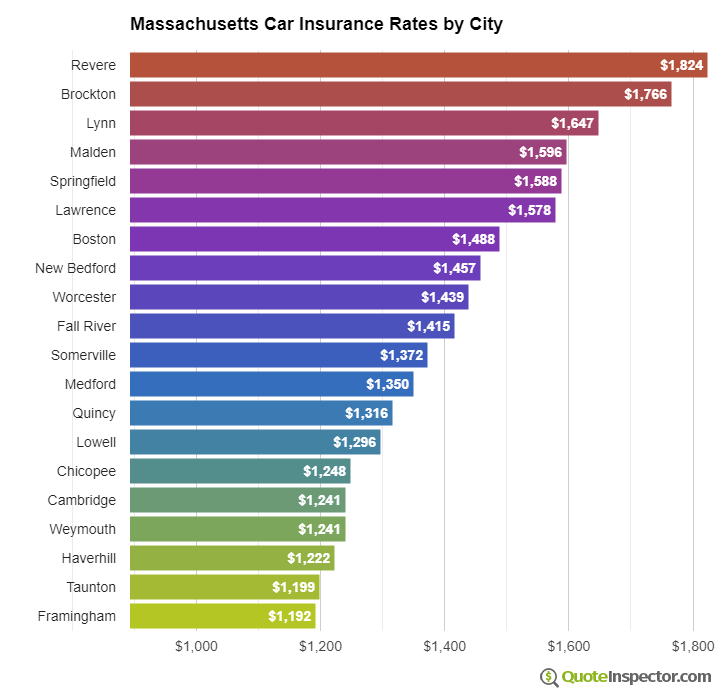
Your ZIP code can make a big difference in your insurance costs. For instance, drivers in Boston, with its bustling urban environment, often pay more than those in quieter towns like Amherst. Why? Urban areas tend to have higher rates of accidents and thefts.
Here’s a quick look at average annual premiums by city:
- Boston: $1,800
- Springfield: $1,500
- Amherst: $1,200
As you can see, urban living comes at a price—literally. But if you’re in a smaller town, you might enjoy some savings.
Variations by Vehicle Type
Not all vehicles are created equal when it comes to insurance costs. A sleek sports car might turn heads, but it will also lighten your wallet more than a standard sedan. Here’s why: sports cars are often driven faster and are more expensive to repair.
- Economy car: $1,200
- Luxury sedan: $1,750
- Sports car: $2,200
Pro Tip: Opting for a vehicle with high safety ratings can lead to considerable savings on your premiums.
Tips for Reducing Auto Insurance Costs
Want to save some serious cash on your auto insurance in Massachusetts? It’s easier than you might think. Let’s dive into the best ways to cut down those pesky premiums.
When it comes to lowering your auto insurance costs, you don’t have to sacrifice coverage to see savings. In fact, by following a few strategic steps, you can keep more money in your pocket without skimping on protection.
Optimize Your Coverage
First things first: review your current policy. Are you paying for coverage you don’t need? Drop unnecessary add-ons like rental reimbursement if you rarely use them. Instead, focus on what’s essential: liability, collision, and comprehensive coverage. Keep your deductible high to reduce premiums—just ensure you can afford it if you need to file a claim.
Leverage Discounts and Bundling
Insurance companies offer a myriad of discounts. Are you taking advantage of them? Look for discounts for safe driving records, being a good student, or even for being a part of certain organizations. Consider bundling your auto insurance with your home or renters insurance. This can lead to significant savings—and simplify billing at the same time.
Improve Your Driving Habits
Here’s the deal: your driving behavior directly impacts your insurance costs. Implement tech like a telematics device to monitor and improve your driving habits. Insurance companies reward safe drivers with lower rates. Drive less aggressively and more attentively to reduce risks and keep those premiums in check.
Pro Tip: Installing safety features in your car like anti-theft devices can also help slash insurance costs.
Shop Around and Compare Quotes
Don’t settle for the first offer you get. The best way to find a bargain is to compare quotes from multiple providers. Different insurers weigh factors differently, which can lead to varying prices for the same coverage. Set aside some time to get quotes and see where you can snag the best deal.
Comparing Insurance Providers
Ever wonder which auto insurance provider in Massachusetts gives you the best bang for your buck? Let’s dive into the top players, and I’ll show you how to compare them like a pro.
You might think all insurance companies are the same, but that’s far from the truth. Each one has different offerings, discounts, and pricing structures that can make a significant impact on your wallet.
Top Auto Insurance Providers in Massachusetts
Here’s a quick rundown of some of the leading insurance companies you should have on your radar:
- GEICO: Known for competitive rates and excellent customer service, especially for tech-savvy users with its robust online platform.
- Progressive: Offers a wide range of discounts and a unique Name Your Price tool to tailor coverage to your budget.
- State Farm: A solid choice if you value personalized service with a large network of local agents.
- Liberty Mutual: Provides a variety of coverage options and discounts, including a unique Better Car Replacement policy.
- Allstate: Known for its comprehensive coverage options and the Drivewise app that rewards safe drivers.
Steps to Compare Quotes Effectively
Comparing auto insurance quotes can seem daunting, BUT it’s crucial for getting the best deal. Here’s the deal:
- Gather Your Info: Have your driver’s license, vehicle details, and prior insurance history ready.
- Use Online Tools: Websites like The Zebra or NerdWallet can provide you with side-by-side comparisons in seconds.
- Check for Discounts: Insurers offer numerous discounts. Don’t miss out on savings for good driving records, bundling policies, or safety features.
- Evaluate Coverage Options: Look beyond the price. Make sure the coverage limits and deductibles meet your needs.
- Contact Providers Directly: Sometimes speaking to an agent can uncover additional discounts or tailored options.
Pro Tip: Always compare at least three different providers to ensure you’re getting the best possible rate.
Sample Comparison of Insurance Providers
To give you a clearer picture, here’s an example comparison of insurance providers in Massachusetts:
| Provider | Features | Average Cost |
|---|---|---|
| GEICO | Online tools, multi-policy discount | $1,100/year |
| Progressive | Snapshot program, Name Your Price tool | $1,200/year |
| State Farm | Local agents, Steer Clear program | $1,250/year |
| Liberty Mutual | Better Car Replacement, multi-vehicle discount | $1,300/year |
| Allstate | Drivewise app, safe driver discounts | $1,350/year |
Legal and Financial Considerations
Did you know that driving without insurance in Massachusetts can cost you a fortune? It’s not just about fines; it’s about putting yourself at serious financial risk.
In Massachusetts, car insurance isn’t just a suggestion; it’s a mandate. But beyond the law, if you skip on coverage, you could end up paying dearly in case of an accident. Here’s the deal: understanding your policy thoroughly can save you from unexpected headaches.
The Legal Consequences of Driving Uninsured
Driving without insurance in Massachusetts is illegal. You could face fines, license suspension, and vehicle impoundment. In some cases, you might even end up with a criminal record. But there’s more to it. If you get into an accident, you’ll have to pay for damages—out of your own pocket.
Financial Risks of Inadequate Coverage
Think minimum coverage will protect you? Think again. With just the basic insurance, you might find yourself on the hook for everything above that limit. That’s a lot of cash. Accidents can cost tens of thousands of dollars, and without adequate coverage, all financial liabilities fall on you. Not just repairs—medical bills, legal fees, and more.
The Importance of Understanding Policy Terms
Have you ever actually read your insurance policy? Most don’t. But it’s crucial. Knowing what’s covered and what isn’t can save you from a nasty surprise. Check for exclusions and limits. Spot those hidden fees or conditions.
Pro Tip: Always, and I mean ALWAYS, review your policy every renewal. Insurers may change terms without you noticing.
Summary
In the winding journey through understanding auto insurance in Massachusetts, knowledge becomes your greatest ally. By being informed about the various factors affecting rates, legal obligations, and smart ways to save, you’re not just a driver—you’re a savvy road warrior. So, the next time you’re asked, “How much is auto insurance in Massachusetts?” you’ll have the tools and insights to speed past uncertainty and drive towards informed decisions.
FAQ
What are the minimum insurance requirements for drivers in Massachusetts?
In Massachusetts, drivers must have a minimum of $20,000 per person and $40,000 per accident in bodily injury liability coverage, as well as $5,000 in property damage liability coverage.
What factors influence auto insurance rates in Massachusetts?
Insurance rates in Massachusetts can be affected by age, driving history, credit score, location, and the type of vehicle you drive.
How can I lower my auto insurance premiums in Massachusetts?
You can lower your premiums by maintaining a clean driving record, bundling insurance policies, taking advantage of discounts, and choosing a vehicle with a good safety rating.
Does my city affect my auto insurance cost in Massachusetts?
Yes, insurance costs can vary significantly by city or region within Massachusetts due to factors like traffic density and crime rates.
What happens if I’m caught driving without insurance in Massachusetts?
Driving without insurance in Massachusetts can lead to severe penalties, including fines, license suspension, and increased insurance premiums in the future.
